
Table of Contents
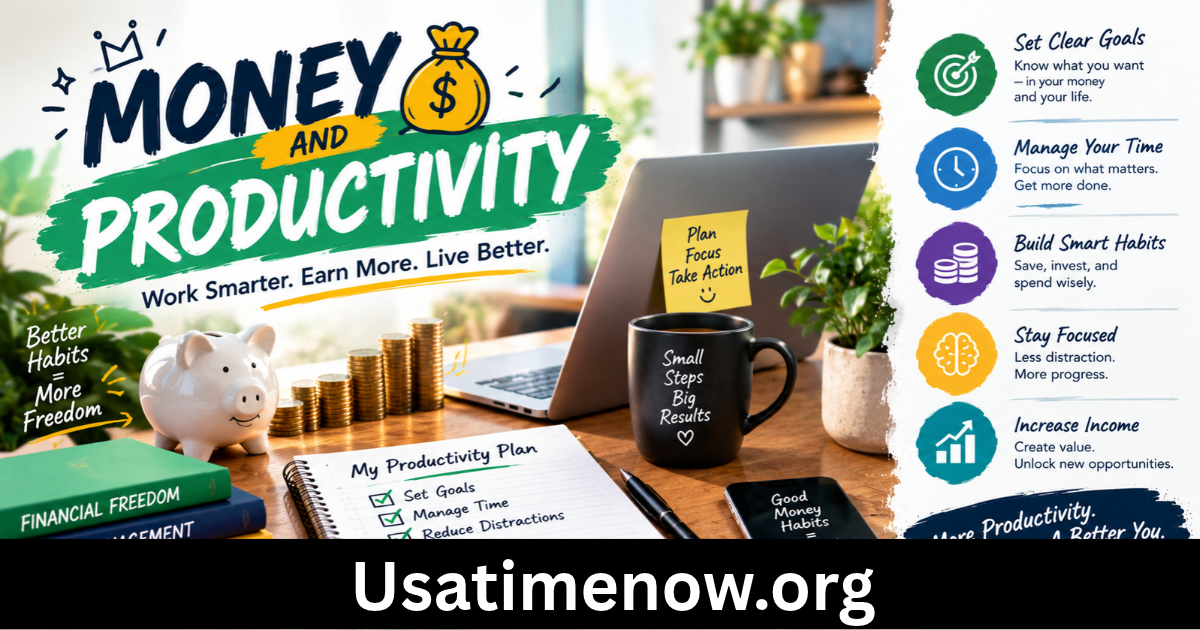
Money productivity is the practice of using your financial resources wisely to achieve better results, reduce waste, and build long-term financial stability. Just as time productivity helps people accomplish more in fewer hours, money productivity focuses on making every dollar work toward meaningful financial goals. Whether you want to save more, reduce debt, manage household expenses, or grow a business, improving money productivity can help you make smarter financial decisions.
In today’s fast-paced world, earning money is only one part of financial success. Learning how to budget, save, spend, and invest responsibly can make a significant difference. By developing practical financial habits, you can improve your relationship with money and create a more secure future.
What Is Money Productivity?
Money productivity refers to how efficiently you manage and use the money available to you. It involves making thoughtful financial decisions, avoiding unnecessary expenses, and directing resources toward priorities that support your goals.
For individuals, money productivity may mean creating a realistic budget, building emergency savings, paying off expensive debt, or planning for future expenses. For businesses, it can involve controlling operating costs, improving cash flow, and investing in activities that generate sustainable value.
The main objective is not necessarily to spend less on everything. Instead, money productivity means getting greater value from your financial resources while maintaining a balance between present needs and future goals.
Why Is Money Productivity Important?
Good money management can reduce financial stress and make everyday decisions easier. When you understand where your money goes, you can identify wasteful spending and make informed choices about what matters most.
Money productivity also supports long-term financial planning. Consistent saving can help you prepare for emergencies, while responsible debt management can reduce interest costs. Setting financial priorities may also help you prepare for education, homeownership, retirement, or business growth.
For entrepreneurs, improving money productivity can reveal which expenses contribute to business performance and which ones provide limited value. This information supports better budgeting and more informed decisions about future investments.
Best Ways to Improve Money Productivity
1. Create a Practical Monthly Budget
A monthly budget is one of the most effective tools for improving money productivity. It gives you a clear picture of your income, expenses, savings, and financial obligations.
Start by calculating your total monthly income. Next, list essential expenses such as housing, utilities, food, transportation, and debt payments. Then identify flexible spending, including entertainment, shopping, and subscriptions.
Compare your expenses with your income to determine where adjustments may be necessary. Your budget should reflect your actual circumstances rather than an unrealistic spending target.
Review your budget regularly and update it when your income or expenses change. A simple spreadsheet or budgeting application can make the process easier.
2. Track Your Spending Habits
You cannot improve your money productivity without understanding how you currently spend money. Tracking expenses helps you identify patterns that may be difficult to notice otherwise.
Record your purchases for at least a few weeks. Group them into categories such as groceries, transportation, bills, dining out, and entertainment.
At the end of the month, review each category and look for opportunities to improve. You might discover that small, frequent purchases are taking a larger share of your income than expected.
The purpose of expense tracking is not to feel guilty about spending. It is to understand your habits and decide whether your money is supporting your priorities.
3. Set Clear Financial Goals
Financial goals give your money a purpose. Without specific targets, it can be difficult to decide how much to save or which expenses to reduce.
Consider dividing your goals into three categories:
- Short-term goals: Paying a bill, saving for a planned purchase, or starting an emergency fund.
- Medium-term goals: Funding education, purchasing a vehicle, or saving for a business project.
- Long-term goals: Preparing for retirement, purchasing a home, or building lasting financial security.
Give each goal a target amount and a realistic deadline. If you want to save a particular amount within a year, calculate how much you need to set aside each month.
Clear goals make it easier to measure progress and maintain motivation.
4. Build an Emergency Fund
Unexpected expenses can disrupt even a well-organized budget. Medical bills, urgent repairs, job changes, and other emergencies may force you to borrow money if you do not have savings available.
An emergency fund provides a financial cushion for these situations. Begin with a small, achievable target and increase your savings as your circumstances allow.
A common longer-term goal is to save enough to cover three to six months of essential living expenses, although the appropriate amount depends on your income stability, responsibilities, and available support.
Keep emergency savings accessible and separate from money intended for everyday spending. This makes it easier to protect the fund for genuine emergencies.
5. Reduce Unnecessary Expenses
Improving money productivity does not require eliminating everything enjoyable from your life. Instead, focus on expenses that provide limited value compared with their cost.
Review recurring subscriptions, bank fees, impulse purchases, and services you rarely use. Compare prices before major purchases and consider whether repairing, borrowing, or buying a suitable secondhand item makes more sense than purchasing something new.
You can also plan meals, prepare shopping lists, and avoid buying nonessential items immediately when you feel tempted.
Small adjustments can create meaningful savings over time, especially when they become consistent habits.
6. Manage Debt Strategically
Debt can reduce money productivity when interest and fees consume income that could otherwise support savings or important goals.
Begin by listing your debts, balances, interest rates, minimum payments, and due dates. Make required payments on time whenever possible to avoid additional fees and protect your credit standing where applicable.
Two common repayment approaches are the debt avalanche and debt snowball methods.
The debt avalanche method prioritizes the debt with the highest interest rate, potentially reducing total interest costs. The debt snowball method focuses on the smallest balance first, which may provide motivation through early progress.
Choose a method you can maintain consistently. If payments have become unmanageable, consider contacting your lender or a reputable financial counselor to discuss available options.
7. Save Automatically
Automating savings can make money management simpler and more consistent. Instead of waiting until the end of the month to see what remains, arrange a recurring transfer to a savings account after receiving your income.
Start with an amount that fits your budget. Even a modest contribution can help establish the habit, and you can increase it when your financial situation improves.
If your income varies from month to month, use a flexible savings plan based on actual earnings and essential expenses.
Automatic saving reduces the number of decisions you need to make and helps you treat savings as a regular financial priority.
8. Use Financial Technology Wisely
Digital tools can make money productivity easier by helping you track expenses, organize bills, and monitor financial goals.
Budgeting applications and spreadsheets can categorize transactions and show spending patterns. Calendar reminders can help you remember payment deadlines, while banking alerts can notify you about account activity.
Choose tools that are secure, easy to understand, and appropriate for your needs. Use strong passwords and multifactor authentication where available, and avoid sharing sensitive banking information with untrusted services.
Technology is most useful when it supports sound financial habits rather than encouraging unnecessary spending or risky financial decisions.
9. Make Thoughtful Investment Decisions
Investing may help you work toward long-term financial goals, but it requires research, patience, and an understanding of risk.
Before investing, consider paying attention to high-interest debt, maintaining emergency savings, and identifying your investment timeline. Learn about different options, including diversified funds, bonds, and other investments available in your country.
Avoid making financial decisions based solely on social media recommendations, promises of guaranteed profits, or pressure to act quickly. Investments can lose value, and higher potential returns generally involve greater risk.
If you need help creating an investment strategy, consider consulting a qualified financial professional who understands your circumstances.
10. Review Your Financial Progress Regularly
Money productivity improves when you measure your results and adjust your approach.
Schedule a monthly financial review. Compare actual spending with your budget, check progress toward savings goals, review debt balances, and identify expenses that may need attention.
Ask yourself whether your current financial habits reflect your priorities. If your income has increased, you may be able to raise your savings contributions. If expenses have grown, you may need to revise your budget.
Regular reviews help you respond to changes early and keep your financial plan practical.
Common Money Productivity Mistakes to Avoid
Several habits can make money management less effective. Avoiding these mistakes can improve your financial decisions over time.
Ignoring small expenses: Frequent low-cost purchases can add up and reduce the money available for savings.
Setting unrealistic budgets: Plans that do not reflect your actual needs are difficult to maintain.
Delaying savings: Waiting until you earn more may prevent you from developing a useful savings habit today.
Making emotional purchases: Buying items to relieve stress or respond to pressure can lead to unnecessary spending.
Ignoring financial risks: Chasing quick profits or trusting unverified investment claims can expose your money to significant losses.
A realistic plan, regular monitoring, and consistent habits can help you avoid these problems.
Frequently Asked Questions (FAQs)
1. What does money productivity mean?
Money productivity means managing your financial resources efficiently to achieve your goals. It includes budgeting, tracking expenses, saving regularly, reducing unnecessary costs, and making informed financial decisions.
2. How can I improve money productivity on a low income?
Start by tracking essential expenses, prioritizing necessary bills, avoiding expensive debt where possible, and saving a manageable amount. Review recurring costs and look for realistic ways to increase income or reduce spending without compromising essential needs.
3. Is budgeting necessary for money productivity?
Budgeting is a valuable tool because it shows how income is allocated and helps you identify opportunities to improve. Although a detailed budget is not essential for everyone, having a clear spending and saving plan can make financial decisions easier.
4. How much money should I save each month?
The right amount depends on your income, living costs, debts, and goals. Start with an amount you can afford consistently. You can gradually increase your savings as your financial circumstances improve.
5. What is the best way to track expenses?
You can use a spreadsheet, a budgeting application, or a written spending log. Choose a method that is convenient enough to use regularly, and review your spending at least once a month.
6. Can money productivity help business owners?
Yes. Business owners can improve money productivity by monitoring cash flow, reviewing operating expenses, planning budgets, reducing waste, and evaluating whether investments support business objectives.
7. How often should I review my financial plan?
A monthly review is a useful starting point. You should also revisit your plan after major changes, such as a new job, a change in household expenses, taking on debt, or reaching an important financial goal.
Conclusion
Money productivity is about making better use of the financial resources you already have while planning responsibly for the future. money productivity By creating a budget, tracking spending, setting clear goals, building emergency savings, managing debt, and reviewing your progress, you can develop stronger financial habits over time.